

One of the most common questions international buyers ask is also one of the most quickly answered: no, you do not need to live in Dubai, hold a UAE visa, or even visit the city to own property here. Dubai is one of the few major global markets where a non-resident foreigner can buy freehold real estate outright, with full ownership rights, managed entirely from abroad.
That accessibility is by design. Since the Freehold Law of 2002, Dubai has deliberately built one of the world's most open property markets for international buyers — and the process has only become more streamlined since, with digital registration, remote purchase mechanisms and clear regulatory protection.
This guide walks through exactly how a non-resident invests in Dubai property in 2026: where you can buy, what it costs, how to complete the purchase remotely, your financing options, the residency it can unlock, and the genuine considerations to plan for as an overseas owner.
- No UAE residency, visa, sponsor or local bank account is required to buy property in Dubai's designated freehold zones
- A valid passport is sufficient to begin — and as of 1 June 2026, the minimum age to own property fell from 21 to 18
- The entire purchase can be completed remotely using an attested Power of Attorney
- Budget roughly 7–10% above the purchase price for transaction costs (4% DLD fee, agent commission, registration, trustee fees)
- Non-residents can obtain mortgages, typically at 50–60% loan-to-value versus 75–80% for residents
- An AED 750,000+ purchase qualifies for a 2-year investor visa; AED 2 million+ qualifies for the 10-year Golden Visa — but residency remains optional
- No annual property tax, no capital gains tax, no income tax on rental income in the UAE — though your home country's tax rules may still apply
Step 1: Understand where you can buy
The single most important rule for non-resident buyers is also the simplest: foreigners can buy freehold property only in designated freehold zones. This is not a restriction on who can buy — any nationality, resident or not, can purchase. It is a restriction on where.
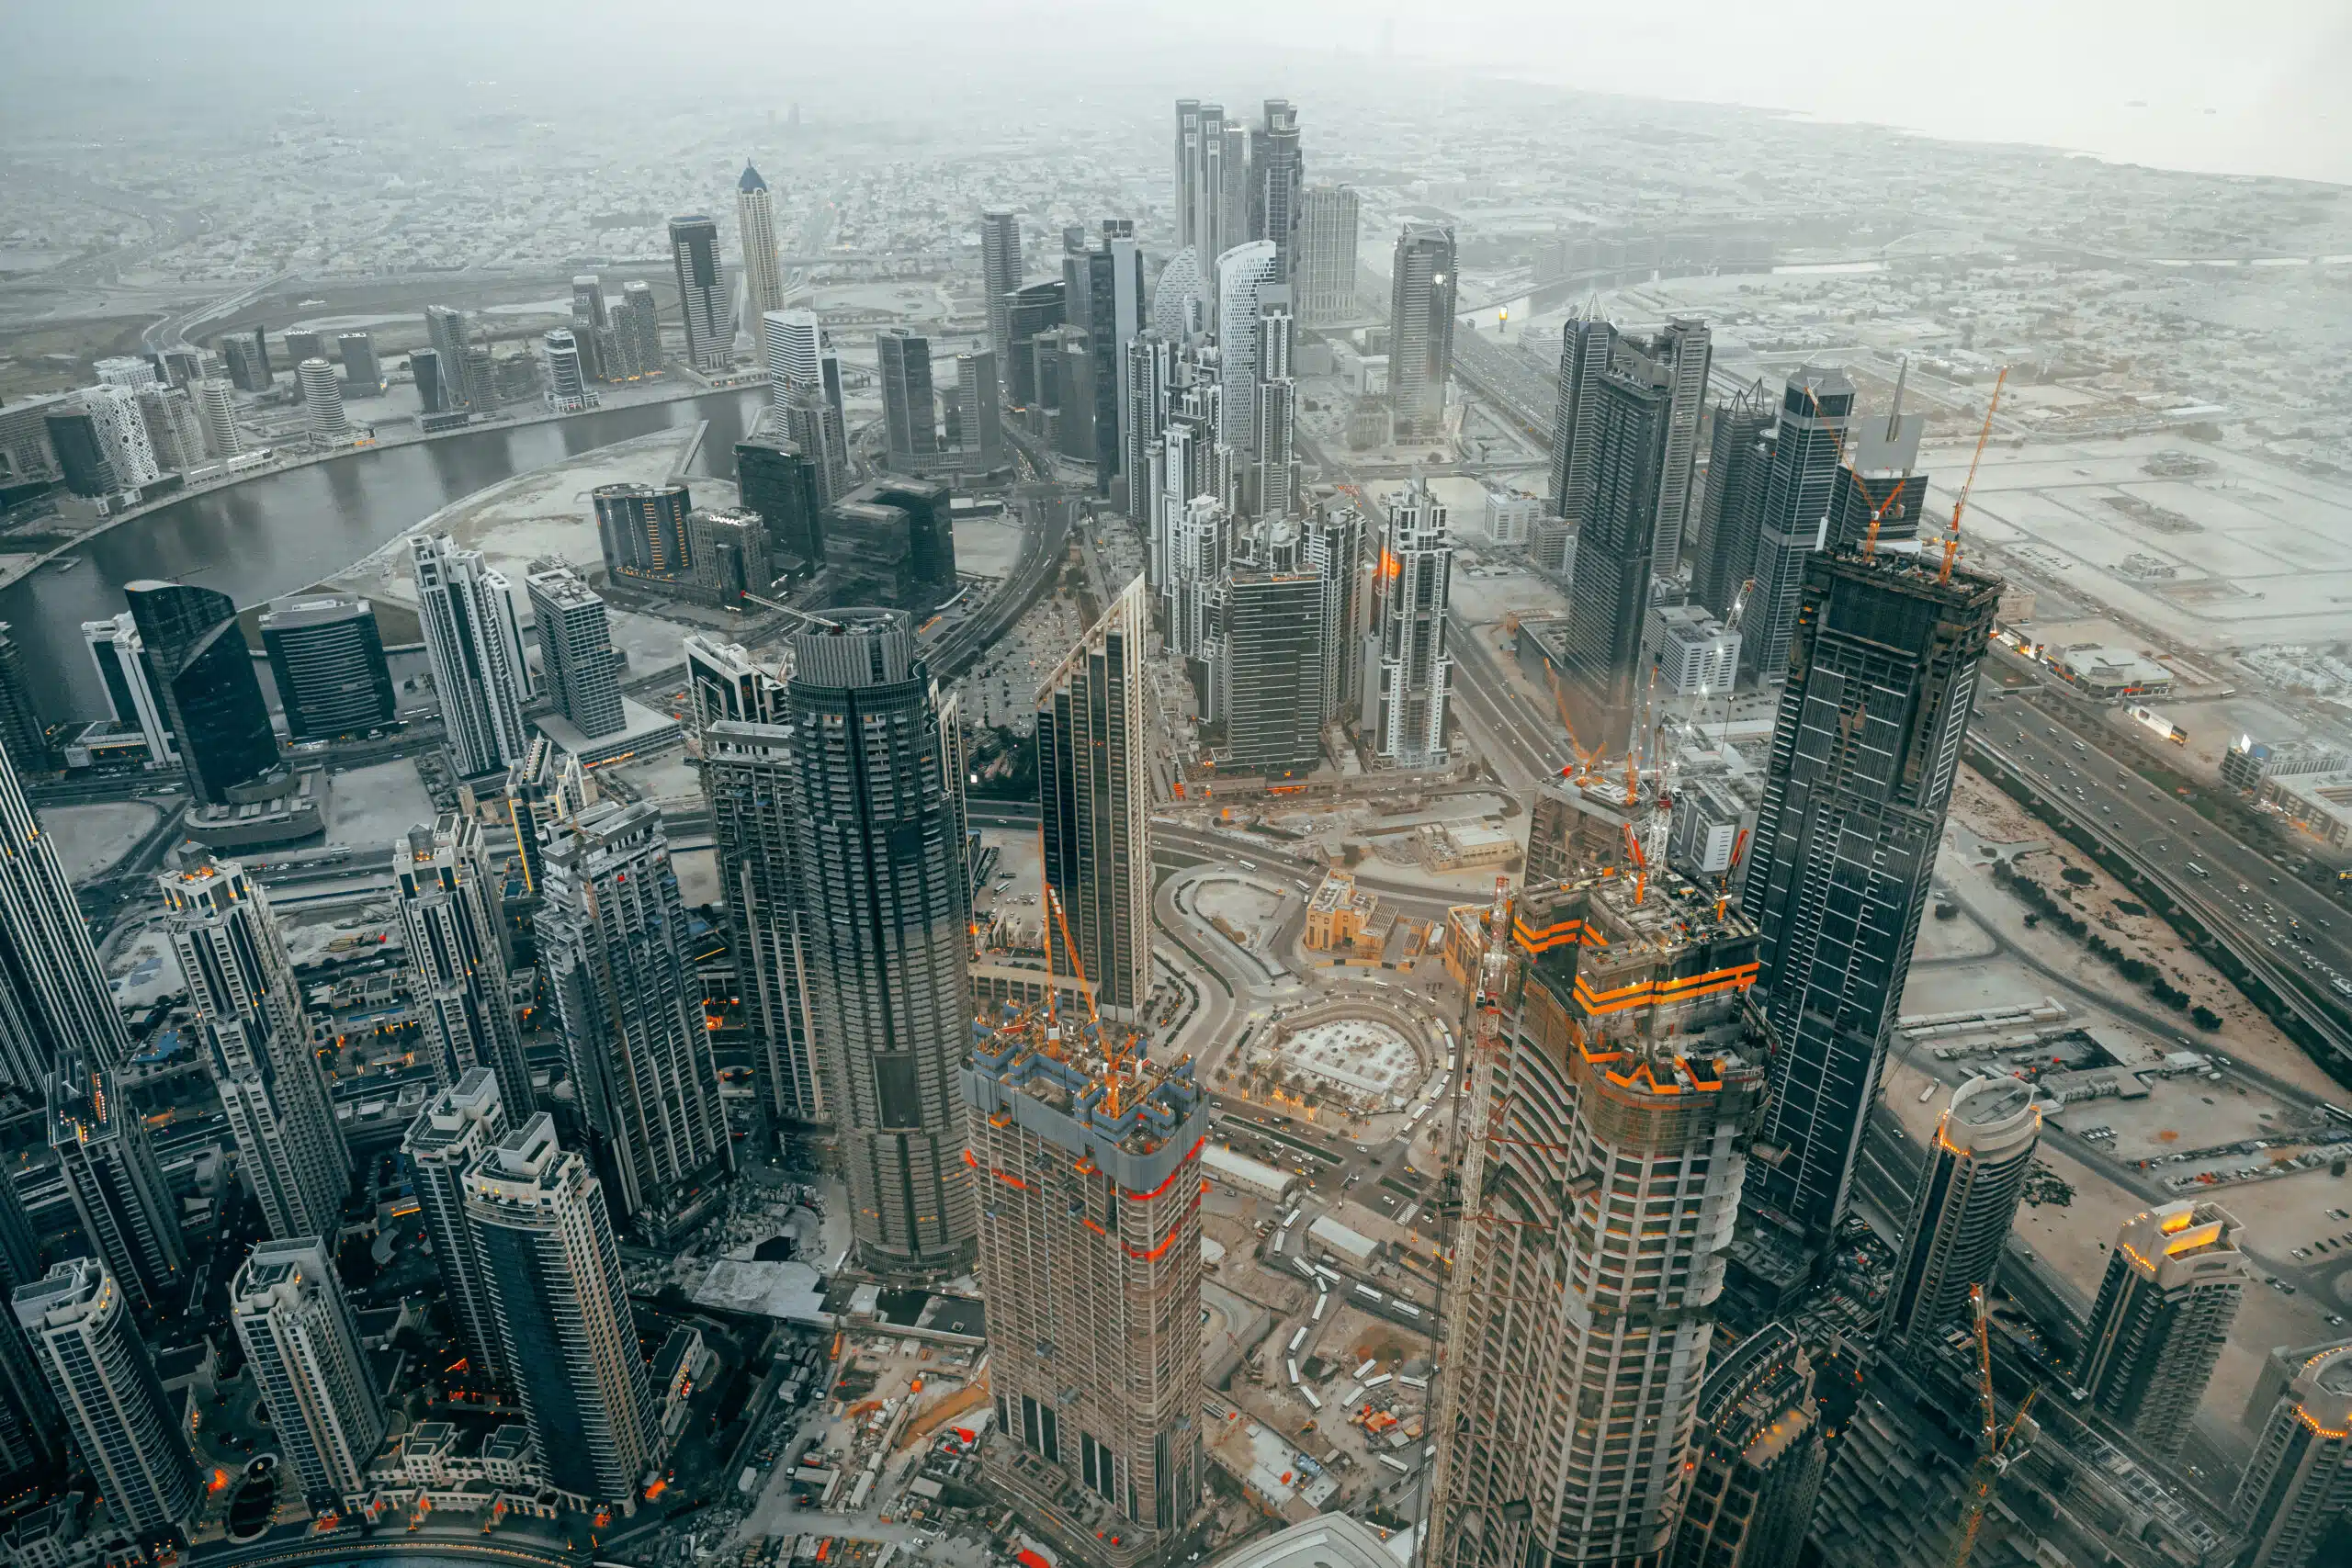
The Dubai Land Department maintains the official list of designated freehold areas, and as of 2026 there are over 60 of them — covering a large portion of the city and including most of its prominent residential and investment communities. Key freehold zones include Dubai Marina, Downtown Dubai, Palm Jumeirah, Business Bay, Jumeirah Village Circle, Dubai Hills Estate, Dubai Creek Harbour, Emaar Beachfront, Jumeirah Garden City, Dubai South, Al Furjan and Al Jaddaf, among many others.
Within these zones, freehold means full ownership of both the property and the land it sits on, indefinitely, with the right to sell, lease or transfer it. Outside designated freehold zones, only UAE and GCC nationals can hold full title — so the first practical step for any non-resident is confirming that the specific property sits within a freehold-eligible area. This can be verified directly through the Dubai Land Department before any commitment is made.
Step 2: Know what you actually need
The eligibility requirements for a non-resident buyer are minimal — far simpler than most Western markets.
You need a valid passport. That is the core requirement. You do not need a UAE residency visa, you do not need a local sponsor, and you do not need a UAE bank account to complete the purchase. The minimum age to own property was 21, but under Federal Decree-Law lowering the UAE's age of legal majority, it dropped to 18 effective 1 June 2026.
Both individuals and companies can hold freehold property, including offshore companies — many investors use special purpose vehicles or family trusts for asset protection and succession planning. There is no cap on the number of properties a foreigner can own, and no nationality, religion or country-of-residence restriction on the buyer's side.
If you are financing the purchase, you will need additional documentation — proof of funds, a bank no-objection certificate and a property valuation report — but for a cash purchase, the documentation requirement is genuinely light.
Step 3: Budget for the full cost, not just the price
The most common mistake non-resident buyers make is budgeting only for the headline purchase price. In practice, you should allow roughly 7–10% above the price for transaction costs.
| Cost | Amount | When |
|---|---|---|
| DLD transfer fee | 4% of purchase price | At transfer |
| Property registration fee | AED 2,100 (under 500K) / AED 4,200 (over 500K) | At transfer |
| Agent commission | ~2% of price + VAT | At transfer |
| Trustee office fee | ~AED 4,000 | At transfer |
| Title deed issuance | ~AED 580 | At transfer |
| Mortgage registration | 0.25% of loan amount | If financed |
| Oqood fee (off-plan) | 4% (off-plan registration) | Off-plan only |
Beyond the transaction, factor in ongoing costs: annual service charges (which vary widely by building and community and directly affect net yield) and the 5% housing fee on rental value collected through utility bills. None of these are taxes in the conventional sense — Dubai has no annual property tax — but they are real costs that an accurate investment model must include.
Step 4: Decide cash or mortgage
Non-residents have both options, but the financing route comes with specific conditions worth understanding before you choose.
A number of UAE banks offer mortgages to non-resident foreign buyers, subject to approval. The key difference from resident financing is the loan-to-value ratio. Non-residents are typically capped at around 50–60% LTV on a first property, meaning a larger down payment, compared to the 75–80% available to UAE residents. Non-residents may also face higher interest margins and a more limited range of lenders and products.
For many international investors, a cash purchase is simpler and faster — and it removes the financing variable from a cross-border transaction that already involves currency transfer and remote coordination. But financing can make sense where it preserves capital for other investments or where leverage improves the return profile. The right choice depends on your individual position; confirming your borrowing capacity with a mortgage broker before committing is the sensible first move if you intend to finance.
Step 5: Complete the purchase — remotely if needed
The buying process for non-residents closely mirrors that for residents, with a few additional documentation steps. The entire transaction can be completed without ever travelling to Dubai, using a properly attested Power of Attorney that authorises a trusted representative to act on your behalf.
Select the property and agree terms
Identify a property in a designated freehold zone, agree the price with the seller or developer, and engage a RERA-registered agent — strongly recommended for first-time and remote buyers.
Sign the Memorandum of Understanding (Form F)
For a resale, buyer and seller sign the MoU (Form F) confirming the agreed terms, and the buyer typically pays a 10% deposit. For off-plan, you sign a Sales and Purchase Agreement (SPA) with the developer.
Obtain the No Objection Certificate (NOC)
The developer issues an NOC confirming there are no outstanding service charges or dues on the property. This is required before the transfer can proceed.
Complete transfer at a DLD trustee office
The parties (or their PoA representatives) meet at a DLD-approved trustee office to settle the balance, pay the fees, and register the transfer. For off-plan, payments are held in a RERA-regulated escrow account released against construction milestones.
Receive your Title Deed
The Dubai Land Department issues the Title Deed in your name, registering you as the legal owner. For cash purchases the process typically takes 2–4 weeks; with a mortgage, 4–8 weeks.
The Power of Attorney is the mechanism that makes remote purchase possible — but it must be specific. Banks, developers and trustee centres may reject a PoA that is too vague or broad, so the document should precisely match the actions your representative needs to perform. It must be properly notarised and attested in your home country and, where required, legalised for use in the UAE.
Step 6: Understand the residency you can unlock
While residency is never required to buy, property ownership in Dubai can unlock it — and for many international buyers, this optionality is a significant part of the appeal.
| Investment | Visa | Duration |
|---|---|---|
| AED 750,000+ | Investor / property visa | 2 years, renewable |
| AED 2 million+ | Golden Visa | 10 years, renewable |
| AED 2 million+ (age 55+) | Retirement visa option | 5 years, renewable |
The Golden Visa at AED 2 million is the most significant option. It provides long-term residency independent of employment, allows you to sponsor your spouse and children, and crucially does not require you to physically live in the UAE to remain valid. As of 2026, Golden Visa eligibility includes mortgaged properties, provided the investor has paid at least AED 2 million of the property value — the previous cash or down-payment requirement was removed. Off-plan properties can also count, generally where the project is at least 50% complete and the investor has paid at least 50% of the value, subject to DLD and immigration approval.
Following the April 2026 unification of the GDRFA and DLD platforms, Golden Visa property-category applications now process in under five working days. Note that while the property purchase itself can be completed remotely, some visa-related steps may still require a short visit to Dubai to complete in-country procedures such as the medical examination and biometrics.
"You do not need a UAE residency visa to purchase property. Non-residents can buy remotely and many do, managing their investment from abroad."
Dubai Land Department investor guidance, 2026
Step 7: Plan for ownership as a non-resident
Buying is the beginning. Owning Dubai property from abroad has its own practical realities that are worth planning for in advance.
You can rent out your property as a non-resident — long-term or short-term — subject to Dubai's rental regulations. Most overseas owners engage a property management company to handle tenant sourcing, rent collection, maintenance coordination and regulatory compliance, particularly for short-term holiday home operations which carry their own licensing requirements.
A UAE bank account, while not required to buy, becomes practically useful for managing rental income, paying service charges and handling day-to-day costs. Note that most non-resident accounts require an in-person visit to a UAE branch to complete identity verification, so many investors open one during a property-viewing trip. Some banks have begun offering remote onboarding, but this varies.
One important recent change affects the exit, not the entry. Under 2025–2026 regulations, when you sell a Dubai property, the sale proceeds must be credited to a UAE bank account owned by you, the registered owner. A Power of Attorney holder can no longer receive sale proceeds on your behalf — PoA financial authority has been restricted to improve transparency and anti-money-laundering compliance. This means non-resident owners should plan to hold a UAE bank account before they reach the point of selling.
What to consider carefully
Verify the freehold zone first. The single most important check is confirming the property sits in a designated foreign-ownership area, and that the seller is the registered owner via the DLD Title Deed verification tool. Do this before paying any deposit.
Your home country may still tax you. Dubai's tax-free treatment applies within the UAE. Most jurisdictions require residents to declare worldwide rental income and capital gains. US buyers additionally face FBAR reporting if UAE accounts exceed USD 10,000 at any point in the year. Check your home-country position before investing.
Use a RERA-registered agent and verify the developer. Remote buyers carry more risk of misrepresentation. A RERA-licensed agent, independent legal representation and developer track-record checks substantially reduce that risk — particularly for off-plan.
Get the Power of Attorney right. A vague or overly broad PoA can be rejected by banks, developers or trustee centres, stalling your transaction. The document must be specific, properly notarised and attested. Errors here are a common cause of delay for remote buyers.
Budget the full cost stack. The 7–10% in transaction costs above the purchase price, plus ongoing service charges, materially affect your true entry cost and net yield. Model the complete picture, not just the sticker price.
Plan your exit banking early. Because sale proceeds must now go to a UAE bank account in your name, open that account well before you intend to sell, not at the last minute.
The bottom line
For a non-resident, investing in Dubai property is genuinely more accessible than in almost any comparable global market. No visa, no sponsor, no requirement to relocate or even visit. A valid passport, a clear understanding of the freehold zones, a properly structured Power of Attorney and a realistic budget that includes the full cost stack — that is substantially what it takes.
The combination of full freehold ownership, a tax-light environment, strong rental yields, a transparent DLD-backed registration system and optional residency pathways is precisely why tens of thousands of international buyers acquire Dubai property each year without ever holding a UAE visa.
The accessibility is real. So is the importance of doing it properly — verifying the zone, checking the developer, structuring the paperwork correctly and accounting for your home-country tax position. Get those right, and Dubai is one of the most straightforward and rewarding markets in the world for a non-resident investor to enter.
The information in this article is provided for general guidance and market awareness. Property laws, fees, visa thresholds, financing terms and regulations are subject to change and should be verified against current Dubai Land Department, RERA and GDRFA sources before acting. Tax treatment depends on your individual circumstances and country of tax residence — seek professional tax advice. Information sourced from DLD investor guidance, Property Finder, Betterhomes and market analysis current as of June 2026. The UAE age of legal majority change to 18 took effect 1 June 2026. Readers should conduct independent due diligence and seek professional legal advice before making any investment decision.
