

Nine square kilometres. Central Dubai. Opposite DIFC, Emirates Towers and the World Trade Centre. Still in active development, with approximately 340 individual building plots sold to developers, most under construction or in early delivery stages.
Jumeirah Garden City is one of Dubai's least understood investment stories — not because the fundamentals are complicated, but because the area does not fit a simple category. It is not a single tower, not a finished community and not a peripheral emerging district. It is a ground-up urban regeneration of Al Satwa, one of central Dubai's most established neighbourhoods, being rebuilt as a medium-density freehold residential district with direct access to Sheikh Zayed Road and the city's most densely employed corridor.
For investors who understand early-stage central-city development, the combination of location, freehold ownership and development momentum makes Jumeirah Garden City worth a serious look in 2026.
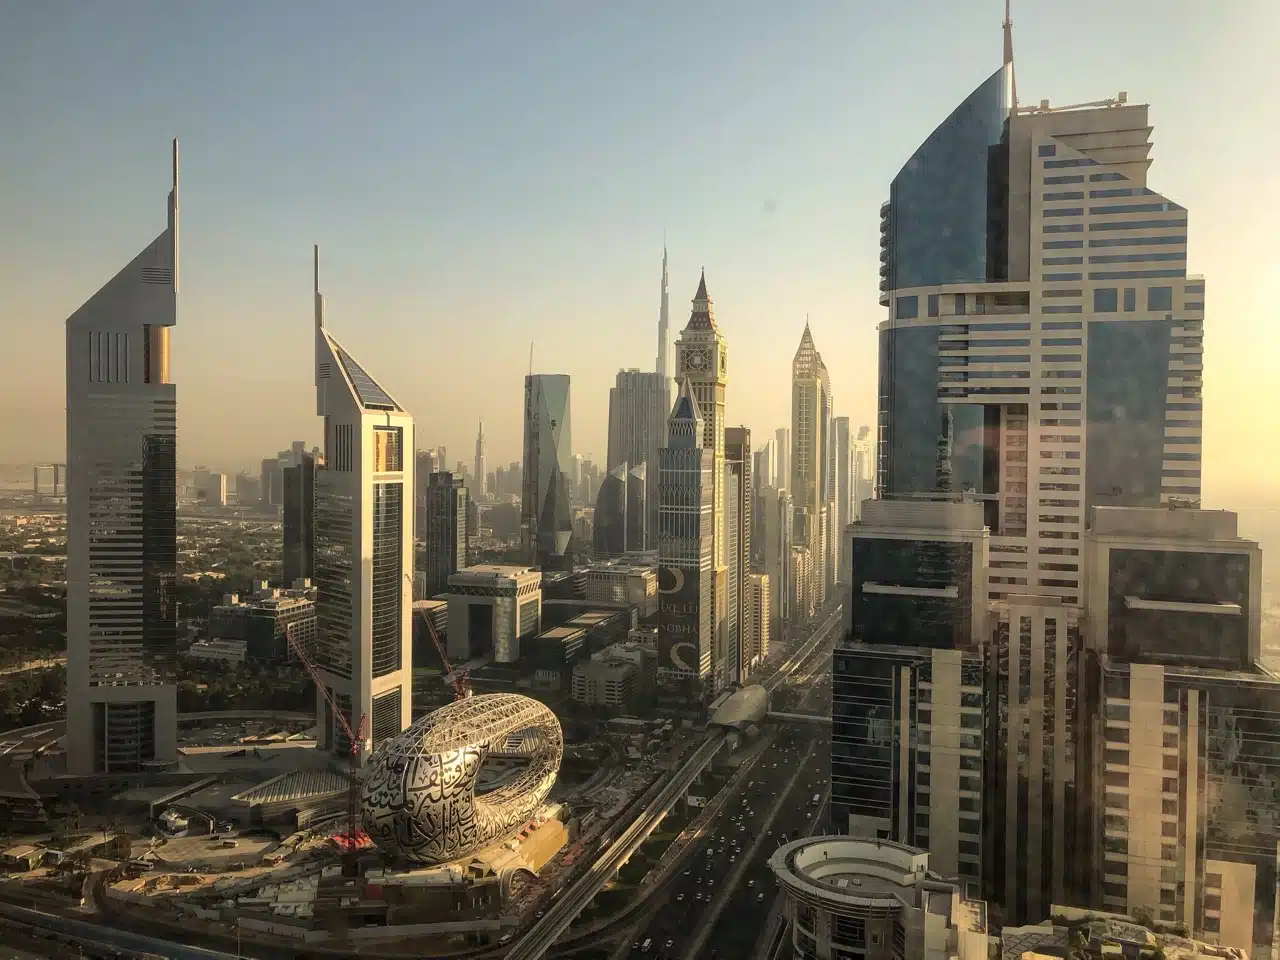
- Jumeirah Garden City covers approximately nine million square metres in Al Satwa, directly north of Sheikh Zayed Road and opposite DIFC, Emirates Towers and the World Trade Centre
- The masterplan is developed by Meraas Holding, which has sold approximately 340 freehold plots to individual developers — buildings are permitted up to ground plus eight floors
- Average price per sqft ranges between AED 1,848 and AED 2,093 depending on building and unit type, based on current listing data
- Gross rental yields average 4.97% to 6.3% across buildings — lower than outer-city areas but supported by the strength of the central location and professional tenant profile
- Average annual rent is approximately AED 124,000 across property types, with average unit sizes around 1,100 sqft
- Dubai International Airport is 14 minutes by car; Downtown Dubai is 10–15 minutes; Jumeirah Beach is 15 minutes
- Brand Centro by EMS Real Estate Development — Lavinia Properties' master broker project — is a residential development in Jumeirah Garden City with Q3 2026 handover
Where Jumeirah Garden City sits in Dubai
The most important thing to understand about Jumeirah Garden City's location is what it is opposite, not just where it is. The development sits in Al Satwa, north of Sheikh Zayed Road (E11), directly across from DIFC, Emirates Towers and the Dubai World Trade Centre — three of the most significant employment concentrations in the city.
This is not a community positioned near the city. It is positioned in the city's working core. A professional employed at DIFC, Emirates Towers or the World Trade Centre corridor can reach their office from Jumeirah Garden City in minutes, not a commute. That proximity to primary employment is the single most reliable predictor of sustained rental demand in any urban residential market globally — and it is the foundation of JGC's investment case.
The community is also well positioned relative to lifestyle destinations. City Walk — one of Dubai's most active leisure and dining destinations — is within the immediate vicinity. The Jumeirah public beach is approximately 15 minutes away. Downtown Dubai with Burj Khalifa and Dubai Mall is 10–15 minutes by car. Dubai International Airport is 14 minutes. These are not aspirational drive times — they reflect the genuine centrality of the Al Satwa location within the wider city.
The masterplan: how Jumeirah Garden City works
Jumeirah Garden City is not a conventional master development where a single developer builds everything. Meraas Holding, one of Dubai's most established government-backed developers — whose portfolio includes City Walk, Bluewaters Island, La Mer and Jumeirah Bay — acquired and cleared the Al Satwa land, developed the infrastructure, roads, utilities and public realm, and then sold individual freehold plots to a range of developers. Those developers then design and build their own buildings within Meraas's masterplan guidelines.
This model creates a deliberately diverse architectural environment. Rather than uniform towers from a single developer, Jumeirah Garden City comprises approximately 340 individual buildings from different developers, each bringing its own design, unit mix and specification. Buildings are limited to ground plus eight floors — creating a medium-density neighbourhood rather than a high-rise district. The masterplan includes residential, commercial, retail, hospitality, parks and public open spaces.
The practical implication for investors is that quality varies significantly by building. Meraas controls the masterplan standards, but individual developer quality ranges from emerging local developers to established international names. Due diligence on the specific building — developer track record, specification quality, service charge structure and management — is more important here than in a single-developer community.
The numbers: price, yield and rental data
All price per sqft figures, average sale prices and rental yields below are sourced from Property Finder and Totality Real Estate market analysis and reflect listing data current at time of publication. JGC is an actively developing area with new buildings entering the market regularly — figures should be treated as indicative. Verify current pricing with DLD transaction records or a licensed agent before making any investment decision.
Pricing in Jumeirah Garden City reflects its central location — it sits between prime areas like Downtown Dubai and Dubai Marina in cost, and the mid-market outer communities like JVC and Silicon Oasis. It is not cheap in absolute terms, but it offers significantly more central positioning than its price point would suggest relative to equivalent locations in other global cities.
Current market data
| Metric | Figure | Source |
|---|---|---|
| Average price per sqft | AED 1,848–2,093 | Property Finder / Totality, mid-2025 |
| Average listing price | AED 1,404,000–1,968,000 | Property Finder, current listings |
| Average annual rent | AED 124,000/year | Property Finder rental listings |
| Average unit size (rental) | ~1,100 sqft | Property Finder |
| Gross rental yield | 4.97%–6.3% | Property Finder by building |
| Entry price (studios) | From AED 982,000 | Developer listings, current launches |
* Prices are indicative based on listing data. JGC is an active development area with significant variation by building. Verify current figures with DLD transaction records before transacting.
The yield range of 4.97% to 6.3% is moderate by Dubai standards — lower than high-yield affordable communities like International City or Dubai Investment Park, but consistent with the profile of a central, professionally-oriented residential area where capital appreciation is the stronger investment thesis rather than pure yield.
"Jumeirah Garden City is the strip behind Sheikh Zayed Road, opposite DIFC, Emirates Towers and the Trade Center. The area is prime, with easy access to DIFC, World Trade Center and Downtown. It is also close to Jumeirah public beach."
DP Navigator, Dubai Property Research
The development pipeline: what is actively being built
Jumeirah Garden City is one of Dubai's most active construction corridors in 2026. Multiple projects are in simultaneous delivery, at various stages from early construction to recent handover. The density of new supply entering the market is both an opportunity and a risk factor — addressed in the caveats section.
| Project | Developer | Status | Unit type |
|---|---|---|---|
| Brand Centro | EMS Real Estate Development | Q3 2026 handover | Studios, 1 & 2-bed |
| Hyde Walk | IMTIAZ | Delivered Dec 2025 | Apartments |
| AYA | Palace Group | Launching 2025, completion 2027 | Apartments |
| Holm Developments debut | Holm Developments | Launched Dec 2025 | Apartments |
| Chelsea Gardens | ALAIA Developments | Launched Jul 2025 | Apartments |
| EVERGR1N House 2 | Object 1 | Under construction | Studios, 1-2 bed |
| 171 Garden Heights | Jad Global | AED 250M investment | Studios, 1 & 2-bed |
The volume and variety of developer activity signals genuine confidence in the location from the development community. Notable among recent launches is Palace Group's AYA — Palace is a hospitality brand associated with the Palace Hotels portfolio, and branded residential launches in JGC represent a step-up in the quality tier of development entering the area.
Brand Centro by EMS Real Estate Development
Brand Centro is Lavinia Properties' master broker project in Jumeirah Garden City. Developed by EMS Real Estate Development — a Turkish developer bringing over 30 years of construction expertise to its Dubai debut — the project is a residential building in Al Satwa offering studios, one and two-bedroom apartments, with handover targeted for Q3 2026.
The development features a rooftop swimming pool, fully equipped gym, central air conditioning, 24-hour security and lobby reception. Interiors reflect EMS's vertically integrated manufacturing capability — the developer operates its own wood and furniture production facility, giving it direct control over interior finish quality. Starting prices were AED 982,000 at launch.
For investors considering Jumeirah Garden City, Brand Centro represents a Q3 2026 entry point into one of Dubai's most centrally positioned development corridors, with a developer whose credentials extend well beyond the UAE property market.
The tenant profile: who rents in Jumeirah Garden City
Location determines tenant profile, and tenant profile determines the durability of rental demand. In Jumeirah Garden City's case, the primary tenant base is professionals working in the DIFC, World Trade Centre and Emirates Towers corridor — one of the highest-income employment concentrations in the Middle East.
This is a meaningful distinction from communities where rental demand is driven by cost-sensitivity. Professionals choosing Jumeirah Garden City are doing so for convenience, not primarily for price. The commute from JGC to DIFC is measured in minutes, not the 30–45 minute road journeys that characterise commutes from more affordable communities like JVC or Silicon Oasis. For someone billing their time at a senior professional rate, that time differential has real monetary value.
The secondary tenant base reflects the neighbourhood's proximity to City Walk and the Jumeirah lifestyle corridor — design professionals, hospitality industry workers, media and creative sector employees who want central city access without paying Downtown Dubai or DIFC rents. This demographic supports consistent demand for well-finished one and two-bedroom apartments with balconies and lifestyle amenities.
Average annual rents of approximately AED 124,000 for a unit averaging 1,100 sqft position JGC as a competitive mid-market option relative to what that same budget would secure in Downtown Dubai or Dubai Marina, where equivalent rents buy significantly less space.
How JGC compares to competing central Dubai areas
| Area | Avg price/sqft | Gross yield | Profile |
|---|---|---|---|
| Jumeirah Garden City | AED 1,848–2,093 | 4.97–6.3% | Developing central |
| Downtown Dubai | AED 2,500+ | ~5% | Prime established |
| City Walk / Al Wasl | AED 2,200–2,800 | 4–5% | Prime lifestyle |
| Business Bay | AED 1,800–2,200 | 5.5–6.5% | Mid-market urban |
| Jumeirah Village Circle | AED 1,100–1,400 | 7–8% | Affordable suburban |
JGC's positioning is closest to Business Bay — mid-market urban, with strong professional tenant demand and yields in the 5–6% range. The key differentiator is that JGC offers a lower price point than the established City Walk corridor while occupying an equivalent or superior physical location relative to the DIFC employment zone.
As JGC matures and infrastructure delivery completes, the expectation among market observers is that pricing will converge toward the City Walk / Al Wasl corridor. The investment case is partially a bet on that convergence happening over a five to ten year timeframe as the approximately 340-building masterplan approaches completion.
What investors should consider carefully
Supply concentration is a short-term risk. Multiple buildings are delivering simultaneously across JGC in 2025 and 2026. A surge of new units entering the rental market in a short window can create temporary downward pressure on rents and occupancy as the stock absorbs. Investors should plan for a stabilisation period of 12–24 months post-handover before expecting peak rental performance.
Developer quality varies significantly. With approximately 340 individual developers building across the masterplan, quality is not uniform. Specification standards, finish quality, service charge structures and property management capability differ building by building. Do not assess JGC as a single homogeneous market — assess the specific building and developer you are buying into. A well-positioned building from a credible developer and a poorly finished building from a first-time developer in the same street will perform very differently.
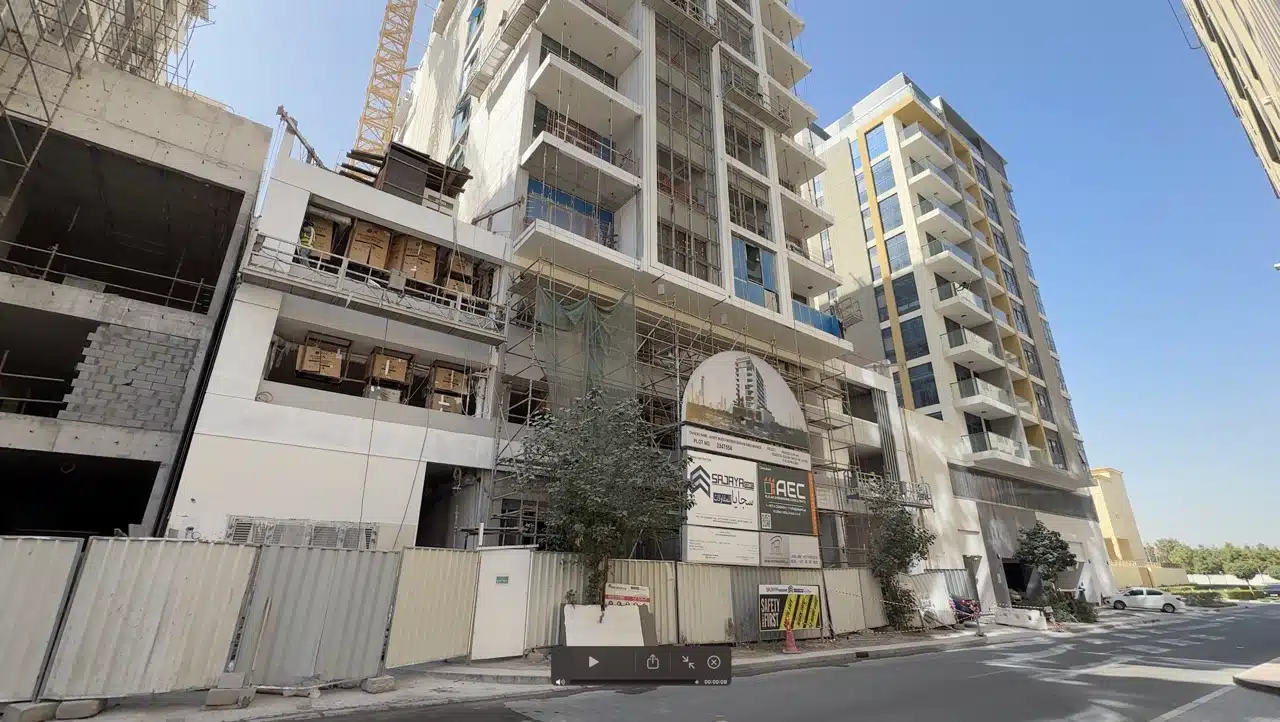
The area is still under construction. Parts of JGC remain active construction sites. The lifestyle and amenity infrastructure that will characterise the completed masterplan is not yet fully in place. Early buyers are purchasing into a trajectory, not an established neighbourhood. The investment case requires patience with that development period.
Yield is moderate, not exceptional. JGC offers 5–6% gross yields — solid for a central location, but not the 8–10% available in Dubai's highest-yield affordable communities. This is a capital appreciation and location play as much as a yield play. Investors whose primary objective is maximum current income should consider whether JGC or a higher-yield community better matches their strategy.
Price data is complex to interpret. JGC's year-on-year price statistics show significant variation because new buildings enter the market at different price points constantly, shifting the "average" in ways that do not simply reflect appreciation or decline. Compare individual building transaction prices over time rather than relying on area-level averages for a true sense of market movement.
The longer view
Jumeirah Garden City's investment thesis is ultimately a simple one: central Dubai land, being rebuilt at medium density, with direct access to the city's primary employment corridor and a government-backed master developer setting the infrastructure standards.
The model has precedent. City Walk — also a Meraas development in the same general geography — was an underdeveloped area that is now one of Dubai's most sought-after lifestyle destinations. The transformation of an underutilised urban area into a high-quality residential neighbourhood through deliberate masterplan regeneration is precisely what Meraas has executed at scale before. JGC is the same formula applied to a larger and arguably more strategically positioned canvas.
The short-term picture is one of supply concentration and construction disruption — unavoidable realities of large-scale urban regeneration. The medium-term picture, as that supply absorbs into a community serving one of the highest-density professional employment zones in the Middle East, is structurally more compelling.
For investors who prefer established communities and predictable near-term income, JGC requires more patience than the current numbers justify. For those with a five-year horizon and conviction in central Dubai's long-term trajectory, the location alone makes it worth the careful analysis.
The information in this article is provided for general guidance and market awareness. Property prices, rental yields and development timelines are subject to change and should be verified against current Dubai Land Department records and official developer communications. Price data sourced from Property Finder, Totality Real Estate and Propsearch.ae, current as of March 2026. Developer information verified against Bayut, Property Finder and Propsearch. Readers should conduct independent due diligence and seek professional advice before making any investment decisions.
